Digital Payment Apps and the IRS: What Small Business Owners Need to Know
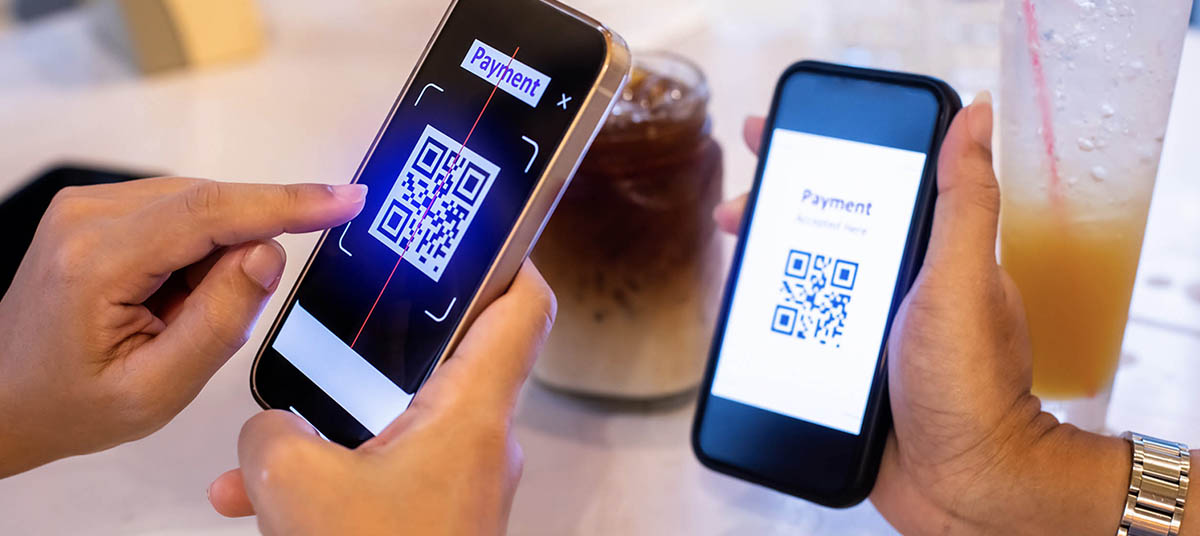
It often begins with a seemingly minor comment: "I only made a little side income this year," or "My clients just send me money through Venmo, so it's off the books." Many small business owners and freelancers operate under the assumption that if a payment feels casual, it is invisible to the tax authorities. Because digital payment platforms are fast, easy, and integrated into our daily lives, they don't feel like formal business systems. However, this casual nature is exactly where many taxpayers find themselves in hot water come April.
For creators, gig workers, and independent contractors, the reality is that the IRS is increasingly focused on the digital economy. Whether you are routing freelance income through Cash App, Etsy sales through Stripe, or consulting fees through PayPal, these transactions leave a digital footprint. Understanding how these platforms report to the government is no longer optional—it is a critical part of modern tax planning for freelancers and entrepreneurs alike.
The Illusion of Privacy in Digital Payments
Over the last decade, payment apps have become the financial infrastructure for the modern small business. The traditional W-2 environment, complete with automated withholding and HR oversight, has been replaced for many by a fragmented ecosystem of digital transfers. While technology has streamlined how we get paid, it hasn't simplified the Internal Revenue Code. In fact, the ease of moving money often leads to a dangerous disconnect between cash flow and tax compliance.
The central question many ask is: "Does the IRS already know about this?" In short, they often do—or they have the right to know. Under IRC Section 61, all income is taxable from whatever source derived, unless specifically excluded by law. This means that whether you receive a formal tax document or not, the burden of proof for reporting that income falls squarely on the taxpayer. When you treat these apps as "invisible" accounts, you are essentially gambling that the lack of a paper trail will protect you, which is a risky strategy in an era of increased data sharing between financial institutions and the government.
The 1099-K Threshold Confusion: Reality vs. Rumor
There has been a significant amount of noise regarding Form 1099-K reporting thresholds. For several years, business owners heard headlines about a proposed $600 threshold that would trigger automatic reporting for nearly every side hustler in the country. However, after various delays and legislative shifts—including the implementation of rules often referenced in the industry as the One Big Beautiful Bill Act—the federal reporting threshold for third-party settlement organizations remains at the higher historic level for now.
Currently, most platforms like PayPal, Venmo Business, and Stripe are required to issue a 1099-K only if you exceed $20,000 in gross payments and have more than 200 business transactions within the calendar year. It is important to note, however, that some states have established much lower thresholds, meaning you might receive a state-level form even if you don't meet the federal requirement. Furthermore, traditional merchant credit card processors operate under different rules and may report transactions regardless of the dollar amount. Relying on the absence of a form to justify not reporting income is one of the most common mistakes that leads to audits and penalties.
The Zelle Distinction and Non-Taxable Transfers
A common point of confusion involves Zelle. Unlike Venmo or PayPal, Zelle typically operates as a bank-to-bank transfer service and does not currently issue Form 1099-K. However, this does not mean Zelle payments are tax-exempt. The platform is merely the delivery vehicle; the nature of the transaction (e.g., payment for services) determines taxability. Conversely, truly personal transactions—such as splitting a dinner bill, receiving a birthday gift, or getting reimbursed by a roommate for rent—are not taxable. The challenge arises when personal and business transactions are commingled in the same app, making it nearly impossible to defend your records during an IRS inquiry.
Why "I'll Figure it Out Later" Is a Costly Strategy
When bookkeeping is treated as a secondary concern, it inevitably leads to one of two outcomes: overpaying taxes because you missed legitimate business deductions near year-end, or underreporting income and facing IRS notices. For many Gen Z entrepreneurs and influencers, the shock of self-employment taxes can be overwhelming. Without a dedicated system to track expenses as they happen, the "extra money" earned throughout the year is often spent before the tax bill arrives, creating a significant cash flow crisis.
Rideshare drivers, online sellers, and part-time consultants often ignore the necessity of quarterly estimated payments. By the time they sit down with a professional, they are facing not just the tax principal, but also accumulated interest and failure-to-pay penalties. The "invisible" money in your Cash App is very visible once the IRS compares your lifestyle and bank deposits against your reported earnings. Organized records are your only shield in these scenarios.
Building a Resilient Financial System
The apps themselves are not the enemy; the lack of a structured system is the true culprit. To protect your business, you must move beyond guesswork. Successful entrepreneurs implement a few non-negotiable habits: they maintain separate business bank accounts, they reconcile their digital payment platforms monthly, and they utilize professional bookkeeping software that integrates with their apps. This clarity allows for proactive tax planning rather than reactive damage control.
By identifying your income streams and categorizing expenses consistently, you can accurately calculate how to lower self-employment taxes through legitimate deductions like home office expenses, equipment depreciation, and health insurance premiums. In a tightening economy with high inflation, preserving your cash flow by avoiding preventable tax surprises is a competitive advantage.
Staying Ahead of the IRS Paper Trail
The digital economy has made earning a living more accessible, but it has also added layers of complexity to tax compliance. If your business relies on Venmo, PayPal, or other digital platforms, now is the time to review your strategy. Waiting until the year-end pressure builds only limits your options for optimization and increases the likelihood of errors.
We specialize in helping modern businesses clean up their books and navigate the nuances of digital payment reporting. If you are concerned about your 1099-K exposure or need a mid-year check-up to ensure your records are audit-ready, reach out to our team today to schedule a tax planning consultation.
Understanding the IRS Automated Underreporter (AUR) System
A critical component of modern tax enforcement is the IRS Automated Underreporter (AUR) system. When a third-party settlement organization (TPSO) like PayPal or Venmo issues a Form 1099-K, a copy is automatically transmitted to the IRS and stored in their Information Returns Master File (IRMF). During processing, the IRS computer systems perform a digital handshake, comparing the amounts reported on these 1099-Ks to the gross receipts you report on your Schedule C or Form 1120-S. If the numbers do not match—specifically, if the reported 1099-K amounts exceed the total income on your tax return—the system automatically generates a CP2000 notice.
A CP2000 notice is not a formal audit, but it is a proposal to adjust your tax liability based on the discrepancy. For small business owners who receive income through multiple apps, this automated matching can create significant headaches. Often, the discrepancy arises because the taxpayer reported their income as a single lump sum, but the IRS received multiple 1099-Ks that, when combined with other income streams, appear to show underreporting. Navigating these notices requires precise reconciliation and a clear paper trail to prove that all income was accounted for, even if it wasn't itemized exactly as the IRS computers expected.
The "Gross vs. Net" Trap of Form 1099-K
One of the most misunderstood aspects of the 1099-K is that it reflects the "gross amount" of all reportable payment transactions. This means the number on the form is the total dollar amount of all payments received for goods or services, without any adjustments. The platform does not subtract processing fees, refunds, chargebacks, or shipping costs before reporting that number to the IRS. For instance, if you sold $25,000 worth of products on Shopify but paid $1,000 in platform fees and issued $2,000 in refunds, your 1099-K will still show $25,000.
Taxpayers who mistakenly report the 1099-K amount as their "net" income are essentially paying taxes on money they never actually kept. To avoid this, you must meticulously track every transaction fee and refund. When filing, you should report the full gross amount from the 1099-K on your tax return and then take the corresponding deductions for fees and returns in the appropriate expense categories. This ensures your return matches the IRS's records while only paying tax on your actual profit. This level of detail is why month-end reconciliation of your digital wallets is just as important as reconciling your traditional bank accounts.
State-Level Reporting: The Patchwork of $600 Thresholds
While the federal government has delayed the implementation of the $600 reporting threshold, several states have moved forward with their own lower requirements. This creates a confusing "patchwork" of rules for business owners. States such as Massachusetts, Maryland, Vermont, Virginia, and Illinois have implemented reporting thresholds significantly lower than the federal $20,000 limit. If you reside in or do business in these states, you may receive a 1099-K from Venmo or PayPal even if your total volume is relatively small.
This state-level data is also shared with the IRS in many cases, which further complicates the reporting landscape. For freelancers working across state lines, it is vital to know the nexus rules for each state where they generate income. If a platform issues a state-specific 1099-K, that income must be properly allocated to ensure you aren't being double-taxed or failing to meet state-level obligations. Keeping your business registration and address updated on these platforms is essential to ensure the correct forms are generated for the correct jurisdictions.
The "Business Profile" Mandate and Terms of Service
Many users attempt to circumvent the reporting rules by using "Personal" profiles for business transactions on apps like Venmo. However, these platforms have become increasingly sophisticated at identifying commercial activity within personal accounts. Using a personal account for business is not only a violation of the platform's Terms of Service—which can lead to your funds being frozen or your account being permanently banned—but it also creates a significant tax audit risk. When you use a "Goods and Services" tag or a dedicated Business Profile, the platform handles the reporting correctly, which actually protects you by providing a clear distinction between taxable income and personal transfers.
From a tax planning perspective, the use of a Business Profile allows for cleaner integration with bookkeeping software like QuickBooks or Xero. These integrations allow you to pull in data automatically, reducing the risk of manual entry errors. It also provides a contemporaneous record that can be invaluable during an audit. If an IRS agent sees a mix of grocery store runs and client payments in a single personal Venmo feed, they are more likely to scrutinize every single transaction, potentially classifying personal gifts as taxable income until you can prove otherwise.
Optimizing Deductions to Lower Self-Employment Taxes
For those earning significant income through digital apps, the self-employment tax (currently 15.3% for Social Security and Medicare) is often a bigger burden than federal income tax. To mitigate this, small business owners must be aggressive and accurate with their deductions. This includes often-overlooked expenses like the home office deduction, which requires a dedicated space used exclusively for business. Additionally, the Section 179 deduction allows you to fully expense certain equipment purchases—like a new laptop or specialized software—in the year they are placed in service, rather than depreciating them over several years.
Other strategies include the Qualified Business Income (QBI) deduction under Section 199A, which may allow eligible self-employed individuals to deduct up to 20% of their qualified business income from their taxes. However, claiming these deductions requires the kind of robust documentation that many "app-based" businesses lack. If you cannot provide a receipt or a clear business purpose for an expense, the IRS can disallow it. This is why transitioning from a casual "side hustle" mindset to a formal "business owner" mindset is necessary as your digital payment volume grows. Proactive tax planning is the difference between a thriving business and one that is constantly playing catch-up with the IRS.
Want tax & accounting tips and insights?
Sign up for our newsletter.